
Report | August 2026

The data center construction boom: risks and claims trends
Key drivers and evolving exposures in a dynamic market.
AI is creating a new infrastructure supercycle
As AI adoption shifts from training frontier models to deploying millions of AI-powered applications and autonomous agents, annual data center investment is projected to rise from around US$500bn in 2024 to more than $1trn as early as 2027. The investment opportunity extends well beyond data centers to electricity generation, grid infrastructure, cooling, networking and semiconductors.
Governments are becoming a major structural driver of AI infrastructure investment. Concerns over technological sovereignty, national security and geopolitical competition have prompted many countries to launch national AI strategies, sovereign compute programs, semiconductor initiatives and direct public investment into domestic computing capacity. Because these investments are driven by strategic priorities rather than purely financial returns, they tend to be relatively price-insensitive, reinforcing the long-term outlook for the sector.
The next wave of investment is becoming global. The US and China are expected to account for around 62% of new global capacity additions through 2030, underscoring their continued central role in the data center build-out and ensuring their combined share of global capacity is expected to remain broadly stable at around 63%. In Europe, Germany, the UK and Ireland are expected to remain major markets, but faster expansion is likely in Spain, Finland and Denmark, where power availability and permitting conditions are often more favorable. Across Asia Pacific, excluding China, installed capacity is projected to increase from around 9GW today to more than 28GW by 2030. Malaysia stands out, with capacity expected to grow more than tenfold, positioning it alongside India and Japan as one of the region’s fastest-growing AI infrastructure markets.
What could slow the infrastructure buildout?
The key constraints are power, permitting and land. Demand for data center financing remains strong as AI demand continues to strengthen. Instead, competitive advantage is increasingly determined by access to electricity, grid connections, permitting, specialized equipment and skilled labor – for example, the US construction industry alone faces a shortage of around 439,000 skilled workers. The winners will increasingly be those that can deploy AI infrastructure fastest, not simply finance it.
The principal risks to the AI infrastructure buildout are increasingly operational rather than demand driven. Infrastructure bottlenecks, supply chain constraints, uncertainty around AI monetization, growing physical climate risks, regulatory hurdles and community opposition will increasingly determine where and how AI infrastructure is built. In the US alone, local opposition delayed or blocked at least 75 projects worth almost US$130bn during the first quarter of 2026, while the Netherlands temporarily froze new hyperscale applications in 2022. Ireland has introduced stricter requirements linking new grid connections to additional renewable generation.
With around 79% of global data center capacity already located in areas exposed to elevated natural catastrophe risk and 54% exposed to chronic heat and drought stress, resilience is becoming a strategic consideration rather than an operational afterthought. Many of the fastest-growing AI infrastructure markets are also among the most climate-exposed. Northern Virginia in the US, Johor in Malaysia and Marseille, France, rank among the highest-risk global markets. In other words, the same factors attracting investment, including abundant land, existing infrastructure and power availability, often coincide with higher climate exposure. Risk profiles also vary by region. Acute flood, wildfire and wind exposure is highest in the Americas, affecting 86% of capacity, while chronic heat and drought stress is greatest in Asia Pacific, where 89% of capacity is exposed.
It is estimated that climate risks could reduce the discounted value of the global installed data center base by around $388bn, equivalent to 38% of asset value before adaptation. Business interruption accounts for almost one-third of total modelled losses, with more than 90% arising from upstream supply chain disruption rather than direct physical damage.
Insurance is becoming a critical enabler of AI infrastructure
As data centers evolve from commercial real estate into mission-critical infrastructure, the role of insurance is expanding beyond protecting physical assets to supporting investment and operational resilience. Comprehensive insurance cover has become a prerequisite for financing many large-scale AI infrastructure projects. Construction costs for a single AI campus can exceed $20bn, with insured values increasing substantially once high-performance computing equipment is installed. Lenders and investors increasingly require robust insurance programs throughout both construction and operation, making insurance an important component of project finance.
The global data center insurance market is projected to grow from around $11bn today to more than $24bn by 2030, reflecting rapid capacity expansion, rising insured values and increasing operational complexity. Demand is expected to extend beyond traditional property cover towards integrated solutions spanning construction, engineering, property, business interruption, cyber and liability, while creating new opportunities in areas such as energy resilience, operational continuity and technology risk.
Top causes of loss
by claims value (% share)
Source: Allianz Commercial
Based on analysis of 221 claims with a total value of approximately €677mn (based on the 100% loss event total, including the shares of other insurers in addition to Allianz Commercial).
Value of claims by region (% share)
Source: Allianz Commercial
Based on analysis of 221 claims with a total value of approximately €677mn (based on the 100% loss event total, including the shares of other insurers in addition to Allianz Commercial).
Top causes of loss
by number of claims (% share)
Source: Allianz Commercial
Based on analysis of 221 claims with a total value of approximately €677mn (based on the 100% loss event total, including the shares of other insurers in addition to Allianz Commercial).
Number of claims by region (% share)
Source: Allianz Commercial
Based on analysis of 221 claims with a total value of approximately €677mn (based on the 100% loss event total, including the shares of other insurers in addition to Allianz Commercial).
The risk landscape and claims trends
As data centers become critical infrastructure for the digital economy, their risk profile is changing rapidly. What were once relatively straightforward, warehouse-like facilities are evolving into large, complex campuses with multi-story buildings, high-density equipment, on-site power generation, advanced cooling systems, and extensive interdependencies with power grids, water supply, and data connectivity.
Construction complexity is a major source of risk. Multi-story data centers create high structural loads and concentrate significant value in a single location. Compressed schedules, late design changes, retrofitting, prototypical or second-hand equipment, poor ground conditions, and inadequate quality assurance can all increase the likelihood of loss. The testing and commissioning phase is especially critical because it is when systems go live for the first time and are pushed close to operating limits. Latent defects, temporary systems, contractor interfaces, and time pressure can allow small errors to cascade into major losses.
Fires in data centers are relatively rare but can have serious consequences. According to Allianz Commercial analysis of insurance industry data center losses, fire is the leading driver of loss severity, accounting for well over 50% of €700mn worth of insurance industry claims. Natural catastrophe activity ranks second, followed by so-called wilful acts (including crime and cyber crime) and power failure. Meanwhile, water damage is the most frequent cause of data center claims, followed by wilful acts, fire, and equipment breakdown. Business interruption is the primary driver of claims severity by line of insurance business, underlining the high financial impact of operational downtime. Europe and North America dominate the share of regional losses according to both the number and value of claims. By claims volume, Europe accounts for 53%, followed by the US at 36%. By severity, Europe accounts for 38% and North America 36%.
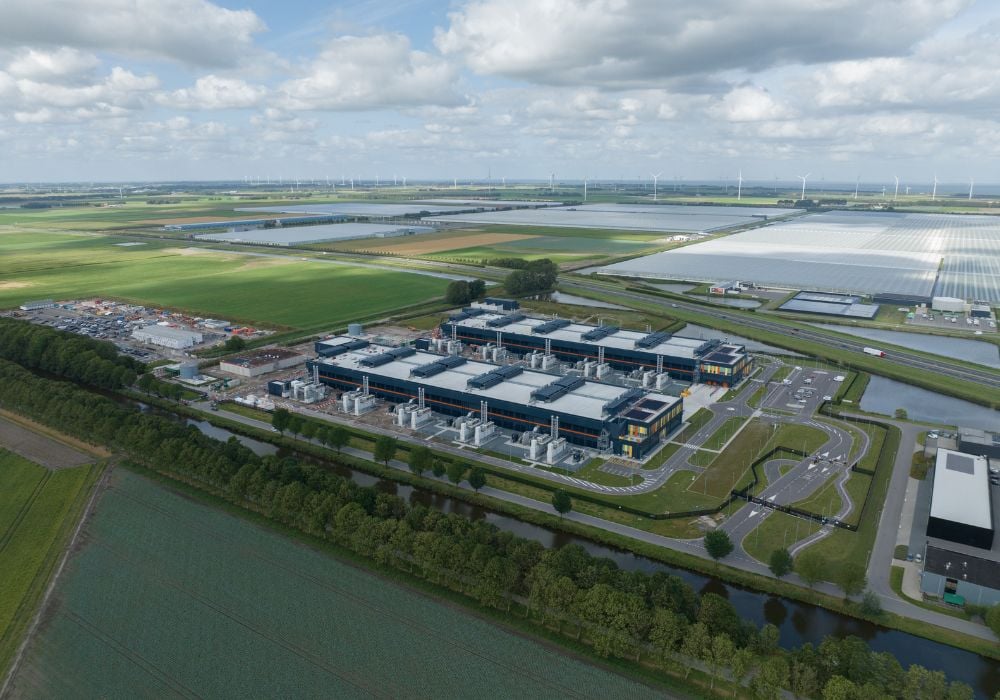
Fire risk is evolving as power density increases and battery energy storage becomes more integrated into facilities. Lithium-ion batteries, increasingly used in or near server environments, can create the risk of thermal runaway – a self-sustaining, high-temperature fire that is difficult to control. Fire suppression systems themselves can also introduce risk, with accidental activation, vibration, noise, contamination, or humidity potentially damaging sensitive equipment. Restoration after a fire can be lengthy and complex, requiring specialist equipment, infrastructure rebuilds, temporary solutions, and careful assessment of whether damaged systems can be safely repaired.
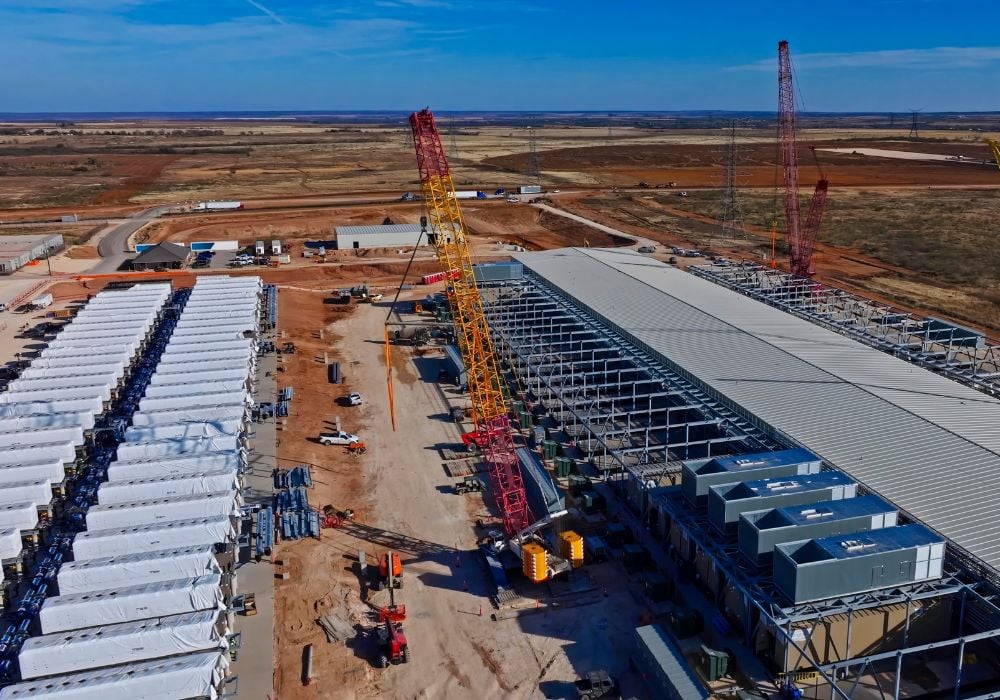
Power is one of the most critical dependencies for data centers. Reliable, high-capacity electricity, redundancy, grid stability, and backup systems are essential to maintain uptime. At the same time, the use of refurbished or prototypical turbines, on-site generation, battery storage, and temporary power systems can introduce new reliability and fire exposures. Water availability is another key dependency, particularly as cooling demands rise and environmental restrictions tighten. Connectivity is equally important, but reliance on external fiber routes and network nodes can create vulnerability to offsite failures.
Hyperscale and colocation facilities create significant accumulation risk. A single campus may bring together operators, multiple tenants, construction works, servers, supporting utilities, and on-site infrastructure in one physical or operational space. One event can therefore trigger claims across multiple insurance policies, including property, construction, business interruption, liability, cyber, and financial lines. Shared infrastructure also means that failures affecting power, cooling, building management systems, or connectivity can have consequences for many stakeholders at once.
Real-life claims case studies show that in hyperscale facilities such loss factors as damage to external cooling systems, hot works-related fire, and a delay in start-up caused by power disturbances have resulted in losses in the €50mn to €100mn range alone.
Claims can also lead to contractual disputes, liability issues, and reputational damage. Failure to meet uptime commitments, power capacity requirements, backup obligations, or service level agreements can result in penalties, service credits, litigation, and customer losses. Supply chain constraints compound this challenge, with long lead times for critical equipment such as switchgear (as long as 80 weeks) and transformers (as long as 50 weeks) potentially extending reinstatement periods and increasing business interruption costs.
Such risk and claims trends developments raise important questions about insurability. Underwriters are increasingly focused on value concentration, site location, natural catastrophe exposure, interdependencies, resilience, business continuity planning, and accumulation across multiple insured interests. Probable maximum loss calculations are often driven by equipment and server values.
Effective risk mitigation must begin early and continue throughout the data center lifecycle. During design, purpose-built facilities, spatial separation, structural load planning, compartmentalization, vertical pathway control, and early fire and battery detection systems are important. During construction, realistic schedules, strong quality assurance, management of temporary systems, and protected equipment storage are essential. During testing and commissioning, adequate time for fault-finding, clear contractor coordination, and a robust safety culture are critical. During operations, preventative maintenance, component monitoring, cooling redundancy, leak detection, fire suppression maintenance, and business continuity planning all help reduce loss potential.
Ultimately, data center risk management requires a holistic and coordinated approach. Owners, operators, tenants, brokers, insurers, investors, contractors, and technology providers need transparency around design changes, tenant changes, scope changes, and operational dependencies. A unified risk framework can help reduce uncertainty, avoid coverage gaps or overlaps, improve claims response, and support the long-term resilience of this increasingly vital digital infrastructure.
Photo: Shutterstock
The Data Center Construction Boom 2026 webinar
The global data center sector is expanding rapidly, driven by AI and cloud demand. This growth is reshaping construction risks and the way they are managed, mitigated, and transferred. In order to discuss data centres' global growth and hot spots, as well as challenges and risks, we hosted the Data Center Construction Boom webinar.
During the 1h 15 min session, Allianz experts shared an overview of the economic and financing outlook, followed by key construction trends and power generation dependencies. We also explored how design requirements are evolving and infrastructure constraints are influencing risk, and how to build with both resilience and future adaptability in mind.
If you missed the session, the recording is now available.
Our experts
Allianz Commercial's insurance experts around the world provided their insights and knowledge to this report.
Further information
All the latest news, reports and hot topics


Sign up to the newsletter
Keep up to date on all news and insights from Allianz Commercial